Do You Really Get IPO Allotments? Or Is It Just A Lottery?
Do You Really Get IPO Allotments? Or Is It Just A Lottery?
Yes, it is a lottery. That is not the interesting part. The interesting part is that every serious sport is also a lottery, and the people who win at them know exactly what their odds are before they walk out to play.
Anyone who has applied to ten IPOs and received nothing has asked this question, usually with some irritation. It deserves a real answer rather than reassurance.
Here is the short one. Yes. In an oversubscribed issue, allotment is decided by a draw. There is no skill in the draw itself, no relationship that helps, no broker who can improve your number. That part is genuinely random.
And here is where most people stop thinking, which is exactly what costs them. Because random does not mean unknowable, and a low probability event is not the same as an unreliable one. The whole of professional sport is built on that distinction. So is this.
Every scoreboard you admire is mostly a record of misses
Start with the most familiar number in Indian sport.
Sachin Tendulkar scored 100 international centuries across 200 Test matches, 463 one-day internationals and a single T20 international. But matches are the wrong unit to judge a batsman by, and this is where most people misread the record. A century is scored from an innings, not from a match — and in a Test a batsman usually bats twice.
Counted properly, Tendulkar batted 329 times in Tests, 452 times in one-day internationals and once in a T20 international. That is 782 innings. Every one of them was a separate opportunity to score a hundred, and 682 of them ended without one.
One hundred centuries from 782 innings is a conversion rate of roughly 12.8 per cent. One century every eight trips to the crease. In Tests alone he was dismissed without scoring at all on 14 occasions.
Nobody has ever looked at that record and called him lucky. Nobody looks at a run of six single-digit scores and concludes the man cannot bat. The record is judged over the career, and the career was built out of repetition.
12.8 per cent conversion rate, repeated 782 times, produced the most celebrated batting record in the game. Hold that number. You will see it again in a moment.
Now take a sport where the margins are even thinner. In his 2024 commencement address at Dartmouth, Roger Federer gave the audience a statistic about his own career that most tennis fans had never heard. He played 1,526 singles matches and won almost 80 per cent of them. Then he asked what percentage of the individual points he had won across those matches.
Fifty-four per cent.
An edge of four points in every hundred. Not forty. Four. That margin, applied over a decade and a half and 1,526 matches, produced twenty Grand Slam titles. Federer's point to the graduates was that he lost nearly half of everything he ever played and it did not matter, because he was playing the season rather than the point.
Neither of these is a motivational story. Both are arithmetic. A modest per-attempt success rate, multiplied by a large number of attempts, executed with a consistent process, produces an outcome that looks extraordinary from the outside. Judge it by the innings and it looks like failure. Judge it by the career and it looks like mastery.
IPO allotment works on precisely the same mathematics. The only difference is that almost nobody bothers to find out what their hit rate actually is.
So what are the odds, honestly?
Our desk has backtested allotment outcomes across more than 400 mainboard issues. The figures below are the blended averages that came out of that exercise, category by category, across a full cycle. These are the numbers to plan against — not any single issue, and not any recent run of issues.
In every category the same two conditions apply. The allotment is capped when the category is oversubscribed, and the category is oversubscribed in roughly ninety to ninety-five per cent of mainboard issues. The capped outcome is therefore the normal outcome.
Look at the retail line again. Twelve to fourteen per cent. One allotment every seven to eight applications.
That is Sachin Tendulkar's century conversion rate, almost to the decimal.
A retail IPO applicant and the most prolific centurion in cricket history convert at very nearly the same rate. One of them is celebrated for it. The other gives up after six attempts and concludes the system is rigged.
Why the ceiling is one lot, or fourteen
The numbers in that last column are not arbitrary, and understanding where they come from changes how you size an application.
In retail, when the category is oversubscribed, the rules force allotment down to the minimum application size and distribute it by draw. The minimum is one lot. So a person who applied for one lot and a person who applied for thirteen enter the same draw and, if they win it, receive the same single lot. The second person simply blocked thirteen times the capital for it.
In the small HNI category, the minimum application is anything above ₹2 lakh. On a typical mainboard issue where one lot costs somewhere around ₹14,000 to ₹15,000, that minimum works out to roughly fourteen lots. When the category is heavily oversubscribed, allotment collapses to that floor. Hence fourteen.
The big HNI category is where the expectation gap is widest, and it is worth being blunt about it. People assume that because allotment in this category works off the size of the bid, a larger application brings home a proportionately larger allotment. In an oversubscribed issue it does not.
Bid ₹10 lakh in the big HNI category of an oversubscribed issue and what you receive is an allotment worth roughly ₹2 lakh. Around fourteen lots. Not a lot-for-lot share of what you applied for — fourteen lots, the same fourteen lots the small HNI applicant beside you receives. The bid size buys you entry into the category and a better draw. It does not scale the allotment.
A 10 lakh application and a 2 lakh allotment. That is the big HNI outcome in an oversubscribed issue, and it is the outcome to plan capital around — not the full bid you placed.
The operative word in all three cases is oversubscribed. Across the issues we have tracked, somewhere between ninety and ninety-five per cent of mainboard IPOs end up oversubscribed in at least one category. Undersubscription is the exception, not the scenario to plan around. Which means the capped outcome is the outcome you should be modelling, always.
Why the gap between categories is this wide
None of these differences are accidents of demand. They are written into how every issue is carved up before a single application is placed, and once you have seen the split you can never unsee it in a subscription table.
Read the two HNI rows together. The big HNI category is allotted exactly twice the shares that the small HNI category is allotted. That is the structural reason we prefer it, and it is not an opinion — it is visible in the application-wise data of every mainboard issue ever filed.
The proof, from live issues
Every exchange subscription table carries an application-wise breakup alongside the share-wise one. It shows how many applications each category can accommodate and how many it actually received. That second table is the one worth reading, because it gives you your allotment probability directly.
The arithmetic is as simple as it looks: divide the applications the category can accommodate by the applications it received, and multiply by a hundred. Equivalently, take the application-wise subscription multiple and turn it upside down.
Allotment chance = (applications reserved ÷ applications received) × 100. Or simply 1 ÷ the application-wise subscription figure. Nothing more complicated than that is happening.
Start with the reservation claim, because the live data settles it without argument. These are the reserved application counts from twelve recent mainboard issues.
Exactly two to one, in every issue, without exception. The 10 per cent and 5 per cent reservations are not a rule of thumb. They are the rule.
Now the part that matters. Here is the allotment chance in each category across those same twelve issues, calculated from their own application-wise breakups. This is a recent sample, shown to demonstrate that the structure holds in live issues — it is not the long-run figure, and the reconciliation follows immediately after.
Twelve issues. Twelve out of twelve in which the big HNI applicant had better odds than the small HNI applicant, by between two and a half and nearly six times. There is no issue in the sample where the middle category won, and there is no market condition in which it should be expected to.
Reconciling the sample with the backtest
That twelve-issue table is a recent sample, and it leans towards large, well-covered issues. A sample of twelve tells you whether a relationship is real. It does not tell you what to expect over a year. For that you need the full backtest, and the two should always be read together.
Read the two middle columns against each other and the discipline becomes obvious. The sample runs hot in every category, retail most of all, because large issues carry large reservations and this particular twelve is weighted towards them. Anyone who set their expectations from a recent run like this would be disappointed by an ordinary year.
So use each for what it is good for. The sample establishes the relationship between the categories — big HNI ahead of small HNI in twelve out of twelve, by roughly three times, which is the structural point and it does not move. The backtest establishes the level — the numbers in the third column, which is what a year of applications should actually be planned against.
And the caveat that outranks both: these are chances of receiving an allotment. They are not chances of making money on it.
A word about the small HNI category
Put the structural reason and the live data side by side and the case closes itself.
The small HNI category is allotted half the shares the big HNI category gets. It then, in issue after issue, attracts more applications than the big HNI category does — look at Glass Wall Systems, where 1,024 reserved applications drew 90,589, against 2,048 reserved drawing 30,718 in the big HNI book. Half the supply meeting three times the demand. The 5.9x gap in that row is not bad luck. It is arithmetic.
So the small HNI applicant commits between ₹2 lakh and ₹10 lakh per issue, receives an allotment once in fifty to sixty-five attempts over the long run, and when it does arrive receives the same fourteen lots that the big HNI applicant receives. Worse odds than retail, at many times retail's capital commitment, for an identical capped allotment.
We do not use it. If the capital is there, the big HNI category is the one that pays for the commitment — double the reservation, and roughly three times the conversion. If the capital is not there, retail is the efficient place to be. The middle is where money goes to wait.
The one lever you actually control
You cannot change the probability of a draw. You can change how many times you enter it.
Every PAN that applies is a separate entry. Four eligible family members applying to the same issue is four entries instead of one, and the probability of at least one of them converting rises steeply — not by four times, but steeply. Here is what that looks like in the big HNI category, working off a ten per cent per-application rate.
Read the first column and the last column together. A single PAN applying to a single issue converts once in ten. Four PANs applying across twenty issues is a near certainty of converting at least once, and on average will convert eight times.
Four PANs is the number we would treat as a working minimum for anybody serious about this. More is better, and the effect is not linear — each additional PAN adds entries to every single issue for the rest of the year, so the benefit compounds across the calendar rather than sitting in one issue.
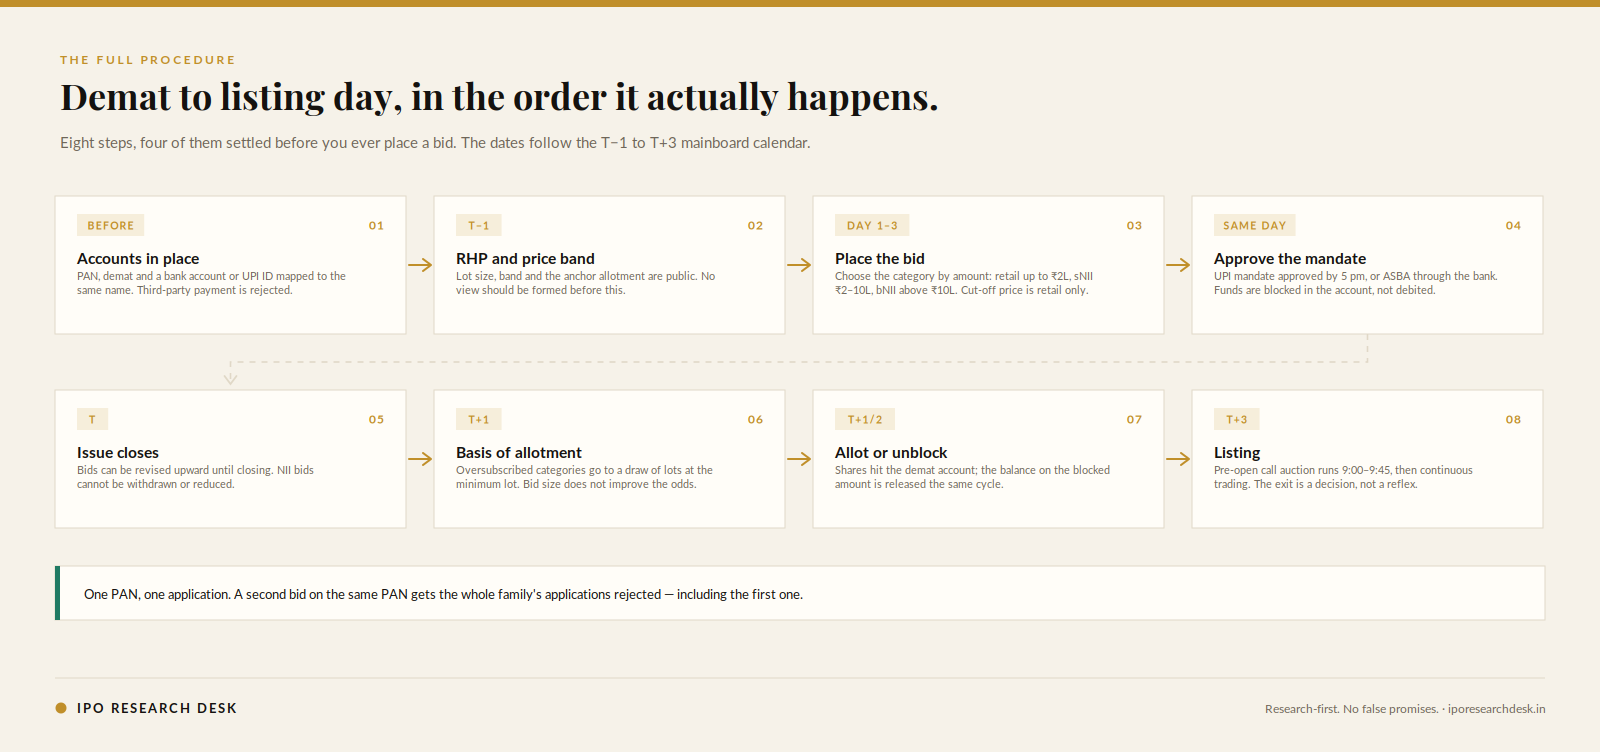
Two conditions, and they are not negotiable. Each PAN must belong to a real person who holds their own demat account and their own bank account, and each application must be funded from that person's own money. Multiple applications under a single PAN are rejected outright — both of them, not just the duplicate. And an application placed in somebody's name with somebody else's money is not a clever workaround; it is a different problem entirely.
What twelve months actually looks like
This is the frame that changes behaviour. Stop counting IPOs. Start counting seasons.
Across the issues we have tracked, a big HNI applicant bidding consistently should expect roughly eight to ten allotments per hundred applications. That is the honest number, and it is derived from outcomes rather than hope. Over an active year with a full mainboard calendar and four PANs bidding, the arithmetic looks like this.
Now notice what this framing does to a bad month. Three issues in a row with nothing is entirely normal at a ten per cent hit rate — it happens about three-quarters of the time somewhere in a thirty-issue year. A batsman who fails three times in a row is not out of form. He is inside the distribution.
What is not normal, and what genuinely does break the model, is stopping. A player who leaves the field after a bad week does not just miss the bad week. He misses the century that was statistically due in the fortnight after it.
The allotment you did not receive is not the problem. The application you did not make is.
And then there is the dropped catch
Any honest person who has followed cricket knows the part the scorecard never records. The edge that falls short of second slip. The catch that goes down on nine. The lbw that was hitting middle and got given not out. A meaningful number of great innings were extended by something that had nothing to do with the batsman.
The same thing happens here, and it would be dishonest to pretend otherwise. Sometimes the allotment arrives in the one issue of the year you almost skipped. Sometimes four applications go out and three convert in a month where the model said one. Call it luck, call it good timing, call it the return on how you have conducted yourself — people find their own language for it and we are not going to argue with anybody's.
But the cricket analogy carries its own discipline, and it is worth stating plainly. A dropped catch only helps a batsman who is at the crease. The umpire's benefit of the doubt only reaches a player who is padded up and playing. Luck does not visit the pavilion.
Every additional PAN, every additional issue you apply to, enlarges the surface area on which good fortune can land. That is the whole of it. You are not manufacturing luck. You are showing up often enough to be in the way of it when it comes.
So — lottery, or not?
It is a lottery on any given day and a probability distribution over a year. Both statements are true, and only one of them is useful.
The person who applies to four IPOs, receives nothing, and decides the whole thing is rigged has drawn a conclusion from a sample too small to support it. Sachin went eight innings between centuries on average. Federer lost forty-six points in every hundred. Nobody drew conclusions about either of them from a fortnight.
Know your category. Know your realistic hit rate. Increase your entries through every legitimate PAN available to you. Apply consistently across a full twelve months rather than selectively in the issues that happen to be loud. And hold the expectation that the data actually supports — eight to ten allotments in a hundred, not a hit every time.
One closing caution, because it matters more than everything above. An allotment is not a profit. Receiving shares in an issue that lists below its price band is a loss delivered efficiently. Everything in this piece is about improving the odds of getting into the issues you have decided are worth getting into. Deciding which ones those are is a different discipline, and it is the one that determines whether any of this was worth doing.
DISCLAIMER
The analysis presented herein is based on publicly available information and data as of the date of publication. This content is published for general information and investor education only and does not constitute investment advice or a recommendation to buy or sell any security. Investors should conduct their own due diligence before making investment decisions. Past performance is not indicative of future results and no guarantee of future performance is offered or implied. The publisher does not guarantee the accuracy, completeness, or timeliness of the information provided. Investment in IPOs and equity markets involves substantial risk, including the risk of loss of principal. Market conditions, company performance, regulatory changes, and macroeconomic factors can significantly impact investment outcomes.